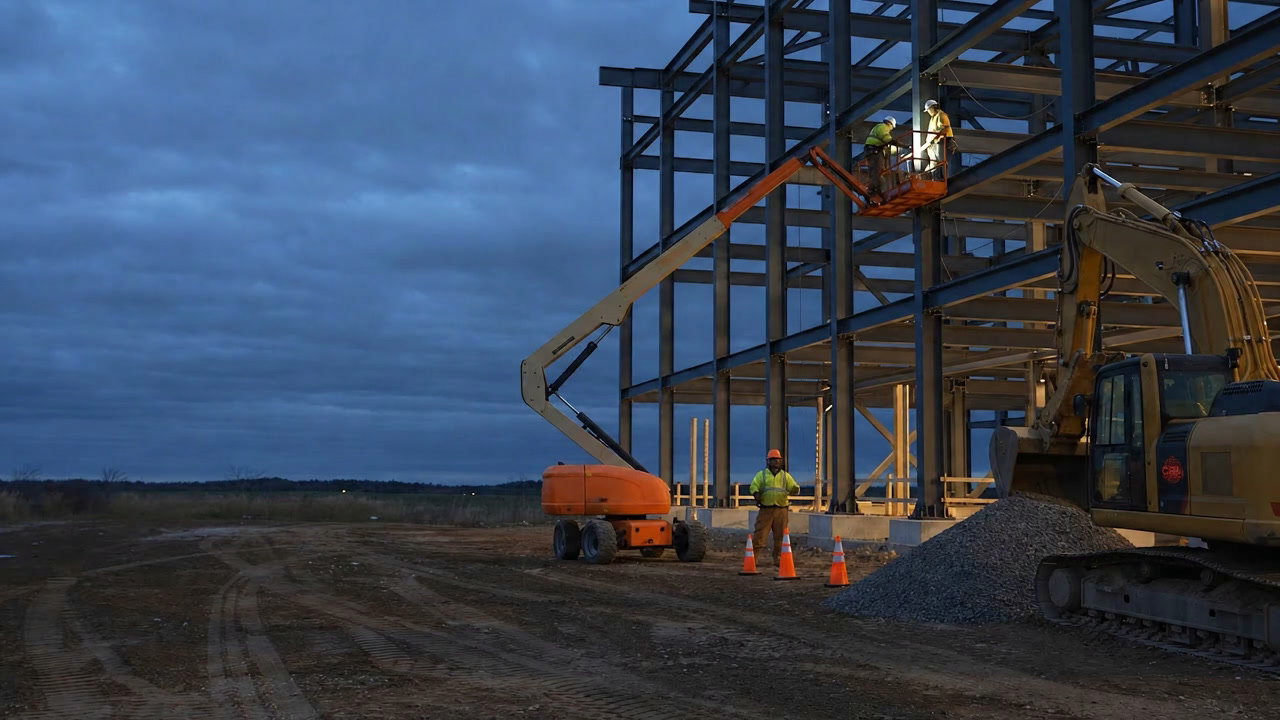
The crew behind the work.
Workers’ compensation starts with accurate payroll, job classifications and subcontractor information.
- Crew and payroll estimates
- Work performed by each trade
- Subcontractor relationships
Commercial insurance
Commercial insurance for businesses of every kind in Connecticut and Texas: BOP, property, general liability, workers comp, commercial auto, liquor liability, cyber and umbrella. Call 203-927-3198
Business insurance.
Built around your business.
Insurance for businesses of every kind in Connecticut and Texas. Review your operations, property, employees, vehicles and liability exposures.
Explore the context
Choose a topic to explore what belongs in your construction insurance review.
Individual terms apply
Workers’ compensation starts with accurate payroll, job classifications and subcontractor information.
Review business vehicle use, drivers, garaging and hired or non-owned auto exposures.
Tools and equipment move between sites. Values, storage, transit and rented equipment belong in the review.
General liability and builders risk serve different purposes. Bring the contract and project details into the conversation.
A focused review
Your trade, project mix, payroll and subcontractor use shape the review. We also consider vehicles, equipment, loss history and contract requirements, including requests for additional insured status or waivers of subrogation. Availability depends on the policy and insurer.
A closer look
Select a topic for details and preparation notes.
Review protection for covered third-party bodily injury and property damage claims arising from your operations. Discuss completed operations, subcontracted work and exclusions that may affect your trade.
Key review points
Review coverage for work-related employee injuries and occupational illness. Accurate payroll, job classifications and subcontractor information are important to underwriting and premium audits.
Key review points
Property insurance for eligible construction or renovation projects. Review the completed project value, materials, schedule and covered causes of loss; liability and workers’ compensation require separate consideration.
Key review points
Review liability and physical damage options for business vehicles. Include driver information, vehicle use, garaging locations and any hired or non-owned auto exposure.
Key review points
Buildings and business contents have different exposures from mobile tools and contractors’ equipment. Review owned and rented equipment, transit, storage, values and deductibles.
Key review points
Consider additional liability limits above scheduled underlying policies. Review required underlying limits, exclusions and how the coverage responds to your contracts and operations.
Key review points
Some operations or loss histories require a specialty-market review. Available placement options, terms and eligibility must be confirmed for your particular risk.
Key review points
Ask about support for applicable bid, performance, payment or license and permit bond requirements. Bond availability depends on the obligation, underwriting and surety approval.
Key review points
Combine eligible commercial property and general liability coverage in one business owners policy. Business interruption options and eligibility vary.
Review liability arising from selling or serving alcohol, including your operations, sales and policy exclusions.
Review data breaches, cyber incidents, response costs and interruption exposures for businesses handling customer data or operating online.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Review coverage for your operations, property, staff and liability exposures.
Planning your review
Requested limits and endorsements deserve attention before work starts. A certificate of insurance summarizes coverage; it does not itself amend the policy. Share your insurance requirements so the applicable policy terms can be reviewed.
Next step Start with what matters to you
Coverage availability is subject to carrier underwriting, eligibility, and applicable state requirements.
Explore contractor insurance by trade to organize the work, equipment and subcontractor details that affect your review.